RSS

This is based on my market — Calgary — but the same theory applies to every Canadian market. Even if your market conditions are much more negative, there’s still a certain point where you pass the peak of the spring market. You just need to take the time to analyze your own numbers. (The change may actually be much more severe than it is here. Believe me, I’ve been through every different type of market. But the main point of this is that one of the keys to success is the ability to quickly adapt.)


Welcome to the late spring market, a significant transition point past the peak of the market in terms of sales volume.

Think you may be past the peak? The answer lies in the trend.

Looking at the weekly and daily stats, I can see that sales climbed steadily throughout April until mid-May, and they’ve been declining ever since. A detailed analysis allows me to accurately state that May 15 was the peak of the market for detached homes in Calgary.


What does this mean in practical terms?


It means that sellers need to adjust their expectations.

1. The available inventory has risen steadily since February 1 and is now about 50 per cent higher than it was then.

2. Sales have steadily declined since mid-May, as mentioned. This trend will continue, with little or no deviation from now until December or January. I can confidently state this, backed by two decades of diligent market observation and analysis.

3. Fewer multiple-offer scenarios are occurring now compared to a month or two ago. This trend will also continue, partly due to different market conditions with more listings and fewer sales, as already discussed. But there’s one more important caveat.

“Early spring” buyers are more willing to jump into multiple-offer scenarios and bid much higher than the list price to get a property. They’re early adopters with a different mindset than “late spring” buyers, who tend to be more conservative and less inclined to write much over asking. (This partly explains why they haven’t bought anything yet!)


Another significant factor your sellers should consider


At any given time, only a limited number of buyers might consider buying in your geographical area and price range. For the sake of simplicity, here’s a breakdown of when 50 theoretical buyers might buy a single-family detached home between March and August:

  • March: 8

  • April: 12

  • May: 12

  • June: 8

  • July: 6

  • August: 4

Based on this, if you wait until July to list a home, 80 per cent of potential buyers have already bought! AND, the remaining buyers have much more inventory to choose from! AND, these remaining buyers tend to be more conservative!


Can you see now why sellers need to adopt a different mindset in the late spring? Anyone can look back on what happened in March, April and May and assume it will be the same moving forward. That’s a huge mistake and one you can help your clients avoid.

Many other factors also affect the market, but “early spring vs late spring” is a significant one that must be considered to achieve success. The bottom line is that in “late spring” (now) it’s even more critical to:

  1. Price it right from the start (not too low and not too high), and

  2. Ensure that your property stands out from the crowd.

As a skilled and experienced agent, you’ll guide your clients in accomplishing both objectives. Even more importantly, you’ll constantly alter your mindset to adjust to changing trends and always tell your clients precisely what you believe to be true.

📞 Your Next Step Starts Here—Contact Me Today!

Tara Kennedy
REALTOR® ABR, RENE, SRS
✨ Tara Kennedy Real Estate 🏘️
☎️ 236-992-8989
🌐 TaraKennedy.ca
📧 TaraKennedySells@gmail.com
🇨🇦 Royal LePage ELITE West

Always Putting Your Best Interest First! 🌟

#TaraKennedyRealEstate #TaraKennedyRealtor #TricitiesRealEstate #CoquitlamRealtor #PortMoodyRealEstate #PortCoquitlamHomes #RoyalLePageEliteWest #BCRealtor #HouseHuntingBC #BuySellInvest #HomeSweetHome #DreamHomeFinder #RealEstateExpert #MoveToBC #RealtorSince2007 #TaraKennedyHomes #TricitiesRealtor #YourTricitiesRealtor #GreaterVancouverRealEstate #InvestInRealEstate #SellingHomes #BuyingHomes #LuxuryRealEstate #RoyalLePageRealtor #TaraKennedySellsHomes
Read

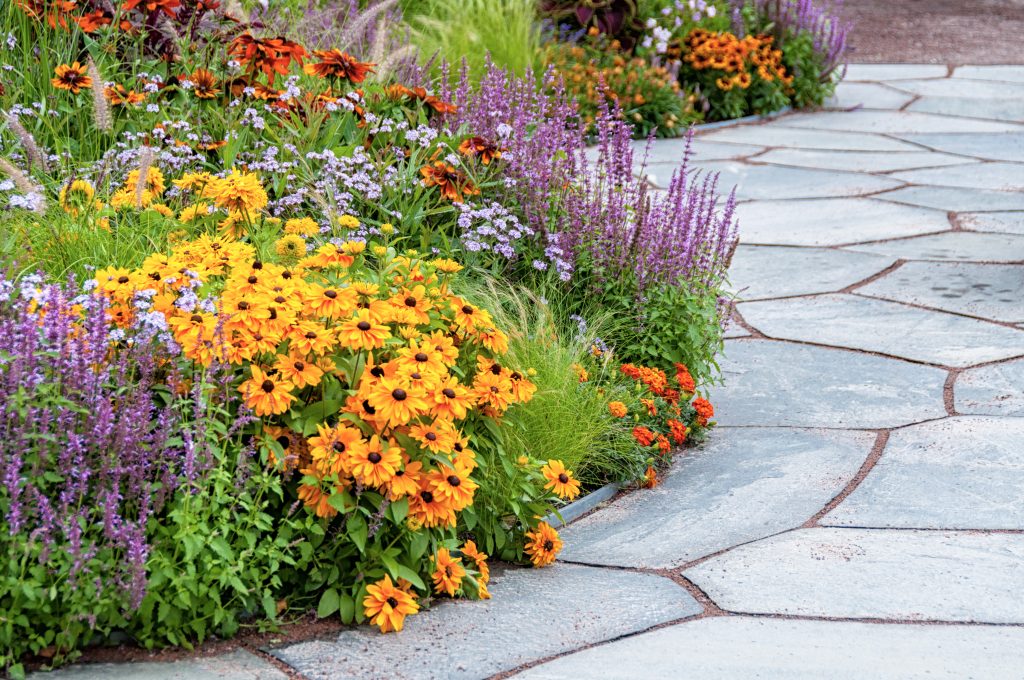
Summer flower bed with Black-eyed Susans and patio stones

In Canada, gardening season is in full-swing now that the sun is shining and temperatures are warmer. This has many homeowners heading to their local greenhouse to pick out some new plants to add to their garden.

If you’re new to gardening, you may want to start off with low-maintenance, robust plants that are easy to maintain without an expert-level of horticultural knowledge.

Before picking out you plants, here are a few mindful tips for the beginner gardener to help you get started:

Sunlight and shade

Put the right plants in the right place! Surprising to some, but not all plants love the sun. Be attentive to where you place your plants in your garden to ensure they’re in a spot optimal for their specific growing needs – some plants thrive in full sun conditions, while others do best in a mix of shade and daylight.

Soil

You’ll be tucking your plants into their garden bed, so it’s important to ensure they’re comfortable. The soil surrounding your home might not be ideal for growing certain types of plants. You can bring a soil sample to your local greenhouse for testing to determine whether or not it’s usable, and if new soil is required.

Water

Some plants are drought-resistant, while others require regular watering. Keep the specific water needs of each plant well documented so your hard work in the garden doesn’t go to waste.

Perennials versus annuals

Before adding any plants to your garden, it’s important to distinguish between varieties that are seasonal and those that stand the test of time. Annuals are the plants that join your garden party for just one season, while perennials are your trusty, long-term garden companions, returning year after year without replanting. Both are wonderful in their own way, adding their unique charm to your outdoor space.

Climate

It’s important to be aware of your surroundings and pick plants and trees that are best for the climate you live in. If you live in a region where temperatures dip below zero, you should also keep an eye on the frost report in your area at the beginning of spring and wait to start gardening until after the frost lifts.

Now that you’re familiar with some basic gardening know-how, here is a list of seven beginner-friendly plants to start with in your garden this year: 
 

Boxwoods are the perfect addition to any garden because they are incredibly resilient. They are drought-resistant, low-maintenance, evergreen shrubs that offer year-round greenery – perfect for the beginner gardener, and loved by even the most seasoned.

1. Boxwoods

Boxwoods are the perfect addition to any garden because they are incredibly resilient. They are drought-resistant, low-maintenance, evergreen shrubs that offer year-round greenery – perfect for the beginner gardener, and loved by even the most seasoned.

2. Hostas

Hostas are the go-to choice for beginner gardeners in Canada because they offer lush greenery while requiring minimal maintenance. They’re perfect to use for lawn borders, ground cover, or adding greenery throughout your property. Hostas are available in different sizes and colours. Place them in partial- to full-shaded areas of your garden – this is where they’ll thrive!

3. Black-eyed Susans

Black-eyed Susans add a beautiful pop of colour to your garden. To grow these blooms in abundance, don’t be afraid to cut them back to encourage abundant blooms — the more you prune, the more they’ll grow. Black-eyed Susans are known pollinators, perfect for attracting bumblebees and butterflies to your garden. These flowers are available in a few different colours, including the most popular variety – yellow! These flowers love the sun, so be sure to plant them in an area with full sun exposure.

4. Garden Phlox

Garden Phlox are available in a variety of colours and smell amazing. Hummingbirds and butterflies love these flowers. They bloom from mid-summer to late fall, and will blossom more vigorously in areas with full sun and ample air flow. Deadhead these pollinators and water them often to have them grow more plentifully.

5. Lavender

Lavender, known for its calming fragrance, is an excellent choice for beginner gardeners due to its resilience and easy upkeep. Lavender thrives in well-drained soil and full sunlight, and is drought-tolerant once established, making it a perfect flower for a beginner’s garden. Be sure to water lavender regularly and prune them lightly after flowering to encourage bushier growth.

6. Daylilies

Daylilies add beauty to your garden with their vibrant and long-lasting flowers. They’re great for beginner gardeners due to their resilience and adaptability. These hardy perennials thrive in various soil conditions and light levels. This makes them easy to grow in almost any garden. Show love to these plants with regular watering and deadheading, and they’ll flourish.

7. Peonies

Peonies are known for their fluffy fragrant blooms and are one of the most commonly used flowers in bridal bouquets. Lucky for the novice gardener who wants to add elegance to their home, these stunning stems are an excellent choice. Not only are they incredibly resilient, but these perennials are available in an abundance of colours.

Happy gardening!

📞 Your Next Step Starts Here—Contact Me Today!

Tara Kennedy
REALTOR® ABR, RENE, SRS
✨ Tara Kennedy Real Estate 🏘️
☎️ 236-992-8989
🌐 TaraKennedy.ca
📧 TaraKennedySells@gmail.com
🇨🇦 Royal LePage ELITE West

Always Putting Your Best Interest First! 🌟

#TaraKennedyRealEstate #TaraKennedyRealtor #TricitiesRealEstate #CoquitlamRealtor #PortMoodyRealEstate #PortCoquitlamHomes #RoyalLePageEliteWest #BCRealtor #HouseHuntingBC #BuySellInvest #HomeSweetHome #DreamHomeFinder #RealEstateExpert #MoveToBC #RealtorSince2007 #TaraKennedyHomes #TricitiesRealtor #YourTricitiesRealtor #GreaterVancouverRealEstate #InvestInRealEstate #SellingHomes #BuyingHomes #LuxuryRealEstate #RoyalLePageRealtor #TaraKennedySellsHomes
Read

Heat pump water pumps are an energy-efficient solution to gas and electric pumps that could save homeowners money.

Boiler system and laundry in a basement interior

urfinguss / Getty Images Plus

More home buyers than ever are choosing energy-efficient heat pump water heaters over fossil-fueled water heaters. In 2022, American homeowners installed over 4 million HPWHs(link is external), and sales of HPWHs increased by 26%. Sales of gas water heaters decreased by 17% for the same period. When homes switch from a standard electric or gas model to a HPWH, they can save as much as one ton of carbon emissions(link is external) each year.

Not only do HPWHs perform up to three times more efficiently than conventional systems, they also last longer and cost less to operate. With the current rebates, tax incentives and low-interest financing options available, now is the prime time for real estate professionals to get up to speed on water heater efficiency to better serve clients.

What should home buyers know before making the switch?

How Heat Pump Water Heaters Work

The HPWH is a highly efficient way to heat water as it transfers heat rather than creating it. The unit is around three times more energy efficient than standard electric or gas models.

HPWHs use electricity to extract heat from the surrounding air to warm water in a storage tank. A fan pulls in the surrounding air and blows it across evaporator coils filled with refrigerant. The warmed refrigerant is pumped through a compressor to increase pressure and temperature before traveling through condenser coils to transfer the built-up heat to the water. After cooling, the refrigerant returns to the evaporator coils and repeats the process.

Benefits of Heat Pump Water Heaters for Homeowners

HPWHs are a cleaner, safer, more efficient and affordable option to heat water. Because the process of transferring heat also draws moisture from the air, HPWHs offer additional dehumidification benefits if installed in a humid environment like a basement.

  • Cleaner & safer: HPWHs eliminate the risk of occupant exposure to carbon monoxide and other indoor air pollutants produced by combustion and also produce fewer greenhouse gas emissions.

  • Efficient: HPWHs are two to three times more efficient than gas or electric options. Effciency means less running time thanks to faster heating. As a result, HPWHs can cut your water heating costs by as much as 50%, depending on how much hot water you use and the type of heater being replaced.

  • Affordable: Nationally, heating water is usually the second-largest household energy expense after space heating and cooling costs and can account for as much as 20%(link is external) of a home’s energy consumption. The average household spends approximately $400–$600 each year on water heating. Switching from a standard electric to a HPWH can cut that in half.

Some states offer rebates or other incentives to encourage your clients to upgrade to a more efficient option. In New York, for example, homeowners can save more than $3,000 between federal tax credits and utility rebates(link is external) with additional rebates coming later this year when Inflation Reduction Act Home Energy Rebates become available.

To learn more about tax credits, rebates and incentives in your market, visit your state or local government’s energy authority.

Installation and Maintenance Considerations

HPWHs are relatively simple to install without major disruptions to your home life. Water heaters are typically located in the basement or garage of a home, and the space must meet certain criteria:

  • Maintains a temperature between 40°F and 90°F

  • At least 500 cubic feet of air space around the water heater or a ducted air source

  • Includes access to pipe condensate to a drain system

  • Access to a 240-volt, 30-amp electrical circuit

For a typical single-family home, the tank will range in size from 50 to 80 gallons, and systems often include a backup heater. While you can find HPWHs sold at most large retailers, be sure to encourage clients to choose a professional installer who can recommend the best location for installation and size based on energy use needs for their homes. Professional installers will also provide any necessary plumbing or electrical needs for proper installation.

Like conventional water heaters, HPWHs require routine maintenance. Performing this maintenance or getting your HPWH serviced regularly can extend the water heater’s life and minimize loss of efficiency. Routine maintenance can include visual inspection for damage, draining once a year to avoid the buildup of sediment or checking the pressure relief valve and anode rod for functionality throughout the year. Alongside this routine maintenance, homeowners should be aware of a few HPWH-specific maintenance checks:

  • Wash the filter: Homeowners should routinely check the air filters. Typically located at the top of the unit, air filters should be checked every few months or when a unit alerts them to the need for cleaning. Filters can be washed using mild detergent or soap. Make sure the filter is dry before placing it back in the water heater.

  • Clean the condensate lines: It is important to clean the condensate drain annually to prevent any backup. To clean condensate drain lines, pour a cup of bleach into the access opening to ensure that no algae, mold, or mildew will form in the pipe throughout the year.

  • Check the operations manual: Before performing any routine or HPWH-specific maintenance, make sure to consult the manufacturer’s operations manual for specific guidance and step-by-step instructions for your particular HPWH model.

Whether your clients are buying or selling, pay attention to the water heating system and consider whether it might be time for a replacement. If the water heater is more than 10 years old, has visible corrosion, or is leaking, it might be time for an upgrade. If a HPWH isn’t an option for the space, there are other energy-efficient options to consider, including electric storage water heaters, electric tankless water heaters, or solar water heaters.

📞 Your Next Step Starts Here—Contact Me Today!

Tara Kennedy
REALTOR® ABR, RENE, SRS
✨ Tara Kennedy Real Estate 🏘️
☎️ 236-992-8989
🌐 TaraKennedy.ca
📧 TaraKennedySells@gmail.com
🇨🇦 Royal LePage ELITE West

Always Putting Your Best Interest First! 🌟

#TaraKennedyRealEstate #TaraKennedyRealtor #TricitiesRealEstate #CoquitlamRealtor #PortMoodyRealEstate #PortCoquitlamHomes #RoyalLePageEliteWest #BCRealtor #HouseHuntingBC #BuySellInvest #HomeSweetHome #DreamHomeFinder #RealEstateExpert #MoveToBC #RealtorSince2007 #TaraKennedyHomes #TricitiesRealtor #YourTricitiesRealtor #GreaterVancouverRealEstate #InvestInRealEstate #SellingHomes #BuyingHomes #LuxuryRealEstate #RoyalLePageRealtor #TaraKennedySellsHomes
Read

Luxury house at dusk in Vancouver, Canada

The number of homes changing hands in Metro Vancouver decreased last month while the number of properties available to buy climbed in tandem. 

In May, the number of transactions recorded over the MLS dipped compared to typical trends for this time of year in Metro Vancouver, according to the most recent insights from Greater Vancouver REALTORS® (GVR). Residential sales hit 2,733 in May 2024, a 19.9% drop from the 3,411 sales the market saw in the same month in 2023. This total comes in 19.6% below the 10-year average for the month of May, which usually hits around 3,398 sales.

This slower pace of sales means the inventory of Vancouver homes for sale has been stacking up. Currently, there are over 13,000 homes actively listed on the MLS, leaving more options for buyers.

“The surprise in the May data is that sales have come in softer than what we’d typically expect to see at this point in the year, while the number of newly listed homes for sale is carrying some of the momentum seen in the April data,” said Andrew Lis, GVR’s director of economics and data analytics, in the board’s monthly release. “It’s a natural inclination to chalk these trends up to one factor or another, but what we’re seeing is a culmination of factors influencing buyer and seller decisions in the market right now. It’s everything from higher borrowing costs, to worries about the economy, to policy interventions imposed by various levels of government.”

New listings on the rise in May

There were 6,374 new listings for detached, attached, and apartment properties in May 2024, a 12.6% increase from the 5,661 new listings in May 2023, and a 7% bump from the 10-year average of 5,958.

Currently, the total number of properties listed on the MLS in Metro Vancouver is 13,600, a staggering 46.3% increase from May 2023, which had 9,293 listings. This number is also 19.9% higher than the 10-year seasonal average of 11,344.

“With market trends now tilting back toward more balanced conditions, as the number of new listings outpaces the number of sales, we should expect to see slower price growth over the coming months,” said Lis. “Up until recently, prices were climbing modestly across all market segments. But with rising inventory levels and softening demand, buyers who’ve been waiting for an opportunity might have more luck this summer, even if borrowing costs remain elevated.”

Sales-to-Active Listings Ratio hovers around 20%

The sales-to-active listings ratio for May 2024, sits at 20.8% across all property types. Here’s a breakdown by property type:

  • Detached homes: 16.8%

  • Attached homes: 25.1%

  • Apartment properties: 22.5%

Home prices generally face downward pressure when the ratio dips below 12% for a sustained period of time. Conversely, when the ratio goes above 20% for several months, we often see upward pressure on home prices.

Home prices see slight increase

The MLS Home Price Index (HPI) composite benchmark price for all residential properties in Metro Vancouver is currently $1,212,000, a 2.3% increase from May 2023, and a slight bump (0.5%) from April 2024.

Here’s how the different property types are faring:

  • Detached homes: Sales reached 846, an 18.9% decrease from May 2023. The benchmark price is now $2,062,600, up 5.9% from last year and 1.3% from April 2024.

  • Apartment homes: Sales reached 1,338, down 22.7% from May 2023. The benchmark price is $776,200, a 2.2% increase from last year but a 0.3% decrease from April 2024.

  • Attached homes: There were 523 sales, a 14% drop from May 2023. The benchmark price is $1,145,500, up 5.2% from last year and 0.9% from April 2024.

📞 Your Next Step Starts Here—Contact Me Today!

Tara Kennedy
REALTOR® ABR, RENE, SRS
✨ Tara Kennedy Real Estate 🏘️
☎️ 236-992-8989
🌐 TaraKennedy.ca
📧 TaraKennedySells@gmail.com
🇨🇦 Royal LePage ELITE West

Always Putting Your Best Interest First! 🌟

#TaraKennedyRealEstate #TaraKennedyRealtor #TricitiesRealEstate #CoquitlamRealtor #PortMoodyRealEstate #PortCoquitlamHomes #RoyalLePageEliteWest #BCRealtor #HouseHuntingBC #BuySellInvest #HomeSweetHome #DreamHomeFinder #RealEstateExpert #MoveToBC #RealtorSince2007 #TaraKennedyHomes #TricitiesRealtor #YourTricitiesRealtor #GreaterVancouverRealEstate #InvestInRealEstate #SellingHomes #BuyingHomes #LuxuryRealEstate #RoyalLePageRealtor #TaraKennedySellsHomes

Read

The cut translates to reduced borrowing costs, but analysts stress that the real impact of the cut will unfold gradually

A for sale sign in the northeast Calgary Cornerbrook neighbourhood was photographed on January 24, 2023.

In a move widely anticipated by economists, the Bank of Canada announced a 0.25 per cent interest rate cut Wednesday, and while the reduction is a step towards easing borrowing costs, industry experts caution that it will take time before any significant impact is felt in the housing market.

The decision to lower the benchmark interest rate to 4.75 per cent comes amid concerns about economic growth and inflation. While the cut translates to slightly reduced borrowing costs, potentially making financing for new construction projects more accessible, analysts stress that the real impact of the cut will unfold gradually.

“We don’t think lower rates will translate into a construction boom. Monetary easing will take time to stimulate projects currently on hold, and Canadian housing construction faces myriad structural challenges. These will likely limit our homebuilding and affordable housing ambitions for the next few years,” Desjardins said in its recent housing outlook.

“Interest rates don’t have an impact on the time it takes to build. It doesn’t have an impact on the approvals process and it doesn’t have an impact on any of the red tape that impacts builders,” said Karen Yolevski, chief operating officer of Royal LePage Real Estate Services Ltd. “So certainly a decrease in rates is welcomed news, but not a silver bullet that’s going to get housing built faster.”

Historical data supports this cautious outlook. Previous rate cuts have often had a delayed response in the real estate sector, as it takes time for lower borrowing costs to translate into increased developer confidence and construction activity. In the short term, developers may remain cautious, still grappling with high material costs, labour shortages, and regulatory hurdles.

“You have to have the zoning, you have to have the materials, and you have to have the labour, so building more homes is going to take time. I don’t think you’re going to see a significant change anytime soon. It’ll slowly increase,” Dream Unlimited Corp. chief executive Michael Cooper said.

However, Cooper explains that when the resale market is sluggish and houses are slow to move, it directly hampers the construction of new homes. “The initial step will be for people to absorb existing inventory, whether through resales or properties held by developers. This absorption is a crucial precursor to any significant increase in new housing construction activity,” he said.

Several other factors continue to exert pressure on the housing market. Stricter mortgage stress tests, introduced to ensure borrowers can withstand higher rates in the future, have indirectly affected the pace of new housing starts. Additionally, rising household debt levels and stagnant wage growth limit the financial capacity of many potential homebuyers, even with lower interest rates, which in turn affects developers’ decisions to start new projects.

“The stress test is still an impediment for some people. It can be a challenge when you’re getting tested at six or seven per cent on your mortgage rate –– those are heavy levels, and I think from a builder’s perspective, if the buying environment is challenging, that does weigh on you,” Bank of Montreal Canadian rates analyst Benjamin Reitzes said.

While the immediate effects of the rate cut might be muted, Reitzes says the long-term outlook offers more optimism.

“Builders are probably quite cognizant of the fact that supply on the resale market is starting to pick up and I’m sure that’ll catch some developers’ eyes to kick-start projects as rates go down.”

Reitzes explained that lower borrowing costs can spur increased demand for housing, as buyers become more confident and financially able. A rise in demand could ultimately stimulate housing starts, offering a much-needed boost to the construction industry. Nevertheless, patience is key.

“If you look at the broader picture for housing, given where prices are, and given where rates are, one of the two of them probably needed to fall today, and it was rates. Whether that’s enough to really balance the market and bring supply and demand back into balance –– we’ll have to wait and see.

Read

The Bank of Canada decided to reduce its target for the overnight lending rate from 5% to 4.75%. The move was widely expected by financial markets and marked the Bank’s first rate reduction since the onset of the pandemic four years ago, bringing rates down to where they stood exactly one year ago.

In a scheduled announcement on Wednesday, June 5, 2024, the Bank noted Canada’s economy picked up in the first quarter of 2024 but still came in weaker than anticipated. While growth in consumer spending, business investment, and the housing market remained solid, the Bank once again made note of the fact that employment has been rising at a slower pace than working-age population growth.

The Bank continues to focus on elevated shelter costs as a significant contributor to inflation. However, it also noted that both headline and core measures of inflation are showing signs of downward momentum and are close to historical averages.

With inflation now back in the Bank’s preferred range of 1-3% and increased confidence that inflation continues to move toward its 2% target, the Bank stated, “monetary policy no longer needs to be as restrictive” in its decision to lower the policy rate by 25 basis points.

The Bank of Canada’s will make its next scheduled interest rate announcement on July 24, 2024, as well as publish its full outlook for the economy and inflation in its next Monetary Policy Report.

📞 Your Next Step Starts Here—Contact Me Today!

Tara Kennedy
REALTOR® ABR, RENE, SRS
✨ Tara Kennedy Real Estate 🏘️
☎️ 236-992-8989
🌐 TaraKennedy.ca
📧 TaraKennedySells@gmail.com
🇨🇦 Royal LePage ELITE West

Always Putting Your Best Interest First! 🌟

Read


How the first interest rate drop in months will impact the housing market. hero image

INTRODUCTION

In a widely anticipated rate announcement today, the Bank of Canada (BoC) has decided to drop the overnight lending rate by 0.25 percent to 4.75 percent. This comes as a welcome relief for many consumers, economists and industry professionals, as Canadians have been weighed down by a high interest for over two years.

The CPI (Consumer Price Index) for Inflation has been steadily decreasing since August 2023 from four percent, coming down over half from the high of 8.1 percent in June 2022. This steady decrease to April’s value of 2.7 percent is a welcome sign that the economy has softened back to manageable levels and inflation has eased to the target band of one to three percent for the Central Bank. This morning’s rate decrease mirrors this sentiment that the Bank of Canada is satisfied with the ease in inflation. That being said, it’s likely that another rate cut might not happen until later in the year as they do not want to be too premature and lead us back into high inflation territory.

alt

How will this impact mortgages and the housing market?

So, what does this mean for consumers? With the rate cut, individuals on variable/adjustable rate mortgages will see a bit of relief in their cost of borrowing. Mortgagors on adjustable rate mortgages should see a payment decrease , whereas borrowers on static variable mortgages will likely not see any change on their payments if they have yet to hit their trigger point on their mortgage. The trigger point of a mortgage is the point at which the monthly payments do not cover the interest of the mortgage anymore and the outstanding balance exceeds a certain percentage of the original purchase price, so the lender would force the borrower to either fix their mortgage into a fixed rate mortgage or pre-pay a lump sum to keep their amortization in line. Many borrowers saw their mortgage hit this trigger point in 2023, so this rate cut would be a welcome change for many individuals that saw their interest rate go up by 4.5 percent or more in the past two years.

Fixed rate mortgages will continue to track the bond market, which moves independent of the prime rate, but decreased borrowing costs will likely offer relief for the fixed rate soon after, as well. With lower rates on the horizon, bond investments become more attractive in the short term which in turn push up the price of bonds and subsequently decrease the yields. Fixed rate mortgages move very closely to government bonds of the same term, so the lower yields on bonds inevitably lead to lower mortgage rates for consumers. We expect this steady decline to continue into Q3 and Q4 of 2024, with rates hopefully settling into the low 4 percent to high 3 percent range, which is consistent with interest rates pre-pandemic.

Consumer confidence in the market has been high, with many waiting on the sidelines to jump once the central bank signals the first cut. With today’s announcement, we expect more buyers to enter the market, which will drive up competition and home prices. We saw an uptick of 4 percent in buyer activity and the Composite HPI (Home Price Index) from January to April already, so lower rates will inevitably increase this value even further. If Q1 2024 was any indication of the real estate market for the rest of the year, we believe a nine percent increase in price by the end of 2024 is not out of the question, compared to the same period last year, based on data from Royal LePage.

Advice for Homeseekers following the rate cut.

For individuals looking to purchase within the next four to six months, I’d highly recommend starting a pre-approval sooner rather than later to ensure you solidify your budget; the market moves quickly so the best thing to do is to be prepared! Have the down payment ready, ensure your mortgage broker or advisor has all the necessary documents, and keep an open channel of communication with your realtor about realistic closing timelines. We’ve already started to see offers go in without subject to financing or other waivers, so we may see more of those as rates drop in the following weeks.

For borrowers who are looking to renew in the next four months, I’d also recommend reaching out to your mortgage advisor to ensure they are securing the best rate for you ahead of renewal. The banks typically do not offer the best renewal rate upfront, so it’s always a good idea to see what other options are available in the market. If rates drop prior to renewal, your advisor can always float the rate down to the new, lower rate, so there’s no disadvantage of starting earlier.

One last note to consider: consumers have been in a high-rate environment for about two years now and we’ve seen prices come down considerably from highs of 2022 due to increased borrowing costs. If you compare the aggregate HPI for Canada over all property types, prices have dropped about 14 percent, reflecting about a $120,000 drop in the benchmark price. Borrowing costs have gone up about 4.5 percent in the same time span, so buyers in this market are still better off than individuals who bought at the peak of 2022 at low rates—a rough savings of around 5 percent or about $43,000 over the past two years, based on the benchmark price. This understandably comes with caveats based on property location, price and whether individuals took a fixed rate mortgage vs a variable rate, but the math holds true when comparing the prime rate over all property types in Canada. With the end in sight, there hasn’t been a better time to buy in the past two years than right now, before market demand catches up with home prices.

As always, our suggestion remains the same to all our clients: invest with intention. We never suggest buyers purchase a property for the sake of a “quick flip” or to try and time the market. If the property fulfills your needs, whether it be for a primary residence or for investment, and the payments are manageable for your long-term goals, purchasing real estate has always been the leading path—albeit not the quickest—towards lasting wealth among Canadian families.

Read

The number of transactions on the Multiple Listing Service® (MLS®) declined in May compared to what is typical for this time of year in Metro Vancouver. This shift has allowed the inventory of homes available for sale to continue to accumulate with over 13,000 homes now actively listed on the MLS® in the region. 


The Greater Vancouver REALTORS® (GVR) reports that residential sales in the region totalled 2,733 in May 2024, a 19.9 per cent decrease from the 3,411 sales recorded in May 2023. Last month’s sales total was also down 19.6 per cent from the 10-year seasonal average for May (3,398). 


“The surprise in the May data is that sales have come in softer than what we’d typically expect to see at this point in the year, while the number of newly listed homes for sale is carrying some of the momentum seen in the April data,” Andrew Lis, GVR’s director of economics and data analytics said. “It’s a natural inclination to chalk these trends up to one factor or another, but what we’re seeing is a culmination of factors influencing buyer and seller decisions in the market right now. It’s everything from higher borrowing costs, to worries about the economy, to policy interventions imposed by various levels of government.” 


There were 6,374 detached, attached and apartment properties newly listed for sale on the MLS® in Metro Vancouver in May 2024. This represents a 12.6 per cent increase compared to the 5,661 properties listed in May 2023 and a seven per cent increase compared to the 10-year seasonal average (5,958). 


The total number of properties currently listed for sale on the MLS® system in Metro Vancouver is 13,600, a 46.3 per cent increase compared to May 2023 (9,293). This total is also up 19.9 per cent above the 10-year seasonal average (11,344). 


Across all detached, attached and apartment property types, the sales-to-active listings ratio for May 2024 is 20.8 per cent. By property type, the ratio is 16.8 per cent for detached homes, 25.1 per cent for attached, and 22.5 per cent for apartment properties.


Analysis of the historical data suggests downward pressure on home prices occurs when the ratio dips below 12 per cent for a sustained period, while home prices often experience upward pressure when it surpasses 20 per cent over several months. 


“With market trends now tilting back toward more balanced conditions, as the number of new listings outpaces the number of sales, we should expect to see slower price growth over the coming months,” Lis said. “Up until recently, prices were climbing modestly across all market segments. But with rising inventory levels and softening demand, buyers who’ve been waiting for an opportunity might have more luck this summer, even if borrowing costs remain elevated.” 


The MLS® Home Price Index (HPI) composite benchmark price for all residential properties in Metro Vancouver is currently $1,212,000. This represents a 2.3 per cent increase over May 2023 and a 0.5 per cent increase compared to April 2024. 


Sales of detached homes in May 2024 reached 846, an 18.9 per cent decrease from the 1,043 detached sales recorded in May 2023. The benchmark price for a detached home is $2,062,600. This represents a 5.9 per cent increase from May 2023 and a 1.3 per cent increase compared to April 2024. 


Sales of apartment homes reached 1,338 in May 2024, a 22.7 per cent decrease compared to the 1,730 sales in May 2023. The benchmark price of an apartment home is $776,200. This represents a 2.2 per cent increase from May 2023 and a 0.3 per cent decrease compared to April 2024. 


Attached home sales in May 2024 totalled 523, a 14 per cent decrease compared to the 608 sales in May 2023. The benchmark price of a townhouse is $1,145,600. This represents a 5.2 per cent increase from May 2023 and a 0.9 per cent increase compared to April 2024.

📞 Your Next Step Starts Here—Contact Me Today!

Tara Kennedy
REALTOR® ABR, RENE, SRS
✨ Tara Kennedy Real Estate 🏘️
☎️ 236-992-8989
🌐 TaraKennedy.ca
📧 TaraKennedySells@gmail.com
🇨🇦 Royal LePage ELITE West

Always Putting Your Best Interest First! 🌟

Read

Down Payment Grants

The standard 20% down payment isn’t always feasible for first-time home buyers, turning them off from the idea of purchasing a home altogether. If this is the case for your client, investigate available down payment assistance options.

 “[Many] lenders have grant programs or down-payment assistance—and in certain cases zero down even for a non-veteran—for first-time buyers who are strapped for cash but desire to own a home,” says Tia Coates, a real estate professional based in Phoenix, Arizona. “There are also zero-down loans for USDA and VA loans for veterans.”

 She says that some grant programs vary state-by-state, but that federal programs from agencies like Fannie Mae and Freddie Mac are available across the country. In some instances, grants of $5,000 or more are available. 

Group Economics

Amid ongoing housing supply challenges and rising prices, many first-time homebuyers are turning to joint ventures or “group economics” in lieu of a solo purchase. In real estate, starting somewhere is crucial, and collaborating as a group often enables greater progress versus acting alone.

 “Typically involving two to four individuals, this strategy entails pooling financial resources and collective purchasing power to acquire property,” says Isaiah Hazward, director of sales for the Coalition Properties Group in Washington, D.C. “By combining their resources, individuals who may lack sufficient funds individually can achieve homeownership collectively.”

Along with getting into a home, this strategy reduces overall financial risk since costs and ongoing maintenance are shared equally among participants. Coates adds that an alternative to this is to utilize a co-signer—such as a parent with well-established credit—to help offset the closing costs and down payment.

NACA Purchase Program

The Neighborhood Assistance Corporation of America (NACA) is a non-profit organization committed to “closing the racial wealth disparity gap through character-based lending.” The nationwide program serves as an economical solution for low-to-moderate income earners buying for the first time.

 “With a proven track record of over $20 billion in mortgage commitments, NACA offers fixed-rate mortgages featuring below-market interest rates, waived down payment and closing costs, and no mortgage insurance, which often creates an increase in purchasing power when compared to traditional loans with mortgage insurance requirements,” explains Hazward. 

Additionally, NACA provides complimentary credit counseling services with no minimum credit requirements for purchases.

Unconventional Purchases

The current housing market guarantees some pretty stiff competition, particularly for first-time home buyers who may not have as much financial leverage compared to those coming in hot with full cash offers. In this case, it may make sense to look into less conventional avenues.

The first option is to consider bank-owned properties in your search, says Tezeta Roro, a real estate professional based in New Jersey. “While the process, decision makers, and paperwork involved is often different from buying from a private owner, it can be a good option for first time homebuyers who may have a hard time competing in the current market due to low down payment,” she says.

Another option is to consider buying from a family member or friend you know. This helps eliminate some competition and can serve as a win-win since it maintains generational wealth. To that end, Roro adds that those looking to downsize can potentially leverage the 1031 exchange tax code to postpone capital gains taxes and buy a property that can be written into a will to be gifted to the adult child, making it a tax-free gift upon death.

Negotiated Seller Concessions

When people talk about what they can afford, they often have a monthly mortgage payment in mind. Coates says that negotiating seller concessions is vitally important to saving your client hundreds of dollars each month. 

“In some areas, we still see sellers willing to pay closing costs for buyers, which helps offset how much the buyer needs to bring to the table,” Coates says. Other examples of seller concessions include covering some maintenance or home repair costs prior to closing, contributing to the down payment, including furniture or appliances in the sale, or buying down the interest rate.

If your clients are feeling the pinch of soaring home prices and inflation, consider whether any of these solutions can relieve financial tension and get them in their dream home sooner than they imagined.

Read

They could save “hundreds of dollars a month” by doing this one simple task, a housing expert says.

Couple has money problems

© South_agency - E+/Getty Images

As mortgage rates once again move above 7% this week, more home buyers may be desperate for savings to better afford homeownership. But housing experts say a common mistake could be costing them thousands of dollars in potential savings: failing to shop around for their mortgages.

Slightly more than half—54%—of recent buyers who recently took out a mortgage say they only gathered one quote from a loan office. But for those who did take the extra effort to shop around, they say their lowest offer didn’t come just from the first lender they contacted, according to a new survey from LendingTree.

“The exact amount that a borrower can save by shopping around for a mortgage will vary based on factors such as the rates they’re offered and the size of their loan,” says Jacob Channel, LendingTree’s senior economist. “That said, it’s not out of the realm of possibility for someone who received multiple offers and then picked the one with the lowest rate to save hundreds of dollars a month, thousands of dollars a year and tens, if not hundreds, of thousands of dollars over the lifetime of their loan.”

Indeed, a separate study from Freddie Mac found that borrowers who received multiple lender rate quotes saved between $600 and $1,200 annually on their home loans. A different survey from LendingTree put the savings at potentially $84,000 over the lifetime of a loan when gathering multiple quotes, or even possibly savings of $234 a month.

Yet, only 22% of recent home buyers say they gathered offers from two lenders, while 14% got offers from three lenders. Only 2% received offers from four lenders, according to the LendingTree survey.

Buyers who gathered just one quote said they mostly did so because they felt confident they received the best rate after contacting just one lender, or they just went with the lender their real estate agent recommended. They also said they felt in a rush to lock in financing due to the competitive housing market, the LendingTree survey finds. Fifty-four percent of buyers say they received their current mortgage from a lender whom they use for other services like checking accounts, auto loans or credit cards.

Older generations tend to be the most likely to accept the first mortgage offer without shopping around (72% of baby boomers, ages 60 to 78) versus 59% of Generation X (ages 44 to 59) and 38% of millennials (ages 28 to 43), according to the survey.

Better Shop Around

Calling multiple lenders may seem daunting, but could be worth it for potential savings—particularly as home buyers find themselves at the top of their budgets. Experts recommend gathering quotes from multiple types of lenders, like banks, mortgage brokers and mortgage banks. Also, The Mortgage Reports recommends gathering quotes from at least three to five lenders, and comparing interest rates and lender fees to secure the best deal.

Read

Consumers may be distracted by fancy fixtures and finishes during a home tour, overlooking more serious problems, researchers say.

House model with unhappy face

© werayuth - iStock/Getty Images Plus

Eighty-two percent of home buyers express regrets about their recent property purchase, according to a new survey(link is external) from Clever Real Estate. Their most common regret: buying a home that requires too much maintenance.

Twenty-eight percent of home buyers say they were shocked at the cost and time needed to maintain their property. About one-third placed the blame on the seller for not being upfront about how much maintenance the home required. The second most common reason home buyers cited as a basis for their regret was that the home did not meet all their needs (24%), the survey shows.

Are house hunters getting distracted by a home’s fixtures and finishes while overlooking other key elements? Well, survey respondents rated an updated kitchen, remodeled bathroom and contemporary lighting as the most important during their home search. These home features were rated much higher than more operational aspects of a home, such as having a solid foundation or an updated electrical system, the survey finds.

“Aesthetic changes can certainly add value and style to a home, but buyers should look beyond the facade to a home’s underlying qualities,” write the researchers who authored the Clever Real Estate report. “Cosmetic fixes can mask structural problems that may cause safety hazards and lead to expensive repairs that most buyers want to avoid.”

A home with fresh interior paint—the fourth most important aspect to buyers, according to the survey—is only a fraction of the cost of purchasing a home that has foundation or structural issues, which ranked at the bottom of buyers’ home-shopping priorities. 

Tips to Keep Buyers in Check

Certainly, a home inspector can provide a thorough investigation of a property once a buyer makes an offer. But during initial home tours, buyers can look for a few signs to indicate property condition. Buyers also appreciate reinforcement from their agent: Consumers say one of the top benefits of using a real estate professional is to have an experienced eye point out unnoticed features and faults of a property, according to the National Association of REALTORS®’ 2024 Home Buyers and Sellers Generational Trends Report.

House hunters should ask “plenty of questions, even if you think the answer is obvious, as this can help you to gain a better understanding of the property,” advises Bradley Mackenzie, who specializes in property valuations for Stokemont Surveyors(link is external). “Make plenty of notes—both positive and negative—throughout your viewing, as these will come in handy when making decisions in the future. If there’s something that catches your eye, take a picture you can come back to for reference and share for a second opinion. Ultimately, you want to become a sponge and absorb as much information as you possibly can.”

The home insurance firm Hippo offers a printable home tour checklist(link is external), which includes items for yard maintenance, age of appliances and home systems, that buyers can fill out during a showing. Here are a few tips to keep in mind.

  • Ask about maintenance costs. Since maintenance issues tend to be the top buyer regret, home shoppers will want to find out more about annual costs to factor into their purchase decision. They can ask sellers for the average utility costs (e.g. water, electricity, gas and trash collection) as well as any regular maintenance issues or extra fees, such as homeowner’s association dues. Also, a general rule of thumb: Homeowners should budget 1% to 4% of the home’s value for annual maintenance costs.

  • Check on high-use items. “The first things you want to check around the property are the things that will have had or be getting a lot of use,” Mackenzie suggests. Check plug sockets and outlets, scanning for any visual abnormalities, test switches and flush toilets.

  • Find out the age of items. How old is the roof, and has it had any previous issues or repairs? How about the HVAC? Checking up on the age of key components within the home may offer insight into how long they will last until a potential repair or replacement is needed. Check out the “Study of Life Expectancy of Home Components(link is external),” produced by the National Association of Home Builders and Bank of America Home Equity, offering the average length of time for common household systems. Also, depending on the age of the home, you may need additional checks.

  • Watch the smells. “Unpleasant odors can be more than just an unfortunate nuisance,” says Courtney Klosterman, home insights expert at Hippo. “Sometimes, weird smells in the house can be early warning signs of underlying problems that could lead to bigger issues down the road.” Be leery of fishy odors, a possible sign of an electrical issue; an ammonia smell unrelated to cleaning, which is potentially a refrigerator or a washing machine issue; or a damp and musty stench, an indication of a moisture problem, Klosterman says.

  • Check on the house’s orientation. The orientation of the house to the sun may matter to some home buyers, and it could affect heating, cooling and maintenance costs. The home’s direction will have a bearing on how much natural light flows in at certain times of the day. South-facing and East-facing houses tend to get the most sunlight. Experts say that North-facing homes may be less expensive to cool when temperatures rise, but since they tend to get less sun flowing through the windows, they may cost more to heat in the winter.

  • Judge vehicle accessibility. Is there sufficient room for your car in the garage? Is it able to adequately accommodate multiple vehicles? If you have any family members who have a disability, how accessible is your home to parking? Also, another common overlooked item that “can cause real issues down the line is how accessible the home is for delivery drivers. Is it easy to find via GPS?” Mackenzie says. “And is there enough room to maneuver vehicles in the area?”

  • Look beyond the property. Check out the home via Google Maps to see how close it is to neighborhood amenities, such as shops and gas stations. Nearly 80% of consumers rank a “house close to shopping” as a quality of their “dream home,” according to a survey conducted by Lombardo Homes. Buyers also may want to do some test-runs to get a feel for how close items are during rush-hour, such as a drive to schools and parks as well as having access to safe, walkable pathways nearby, Mackenzie says.

  • Look at the structural integrity. A home inspector may recommend further inspections if they suspect any problems. But during a buyer’s initial tour, you may spot some key indicators of poor build quality or underlying problems, such as large cracks throughout the walls. “They can be tricky to spot at times, as some tenants might attempt to cover them over. However, if you make close observations around the doorways, windows and any extensions on the house, you should pick up on any major issues,” Mackenzie says. Hippo provides the following chart to help decipher the meaning behind certain wall cracks.

    Wall cracks you shouldn't ignore

    Source: Hippo, hippo.com

Read

INTRODUCTION

When I opened up the latest stats from Greater Vancouver Realtors, I was taken aback by the sheer volume of listings on the market in the Lower Mainland - more than 12,000. That is a lot for any market.

So what’s causing this spike in homes on the market? I have my own suspicions based on conversations from our partners in both British Columbia and Alberta. I presumed this increase in listing activity was primarily due to inter-provincial migration to Alberta and I suspect that’s still part of what’s happening.

When I reached out to REW partner Ty Corsie from Royal LePage - Wolstencroft, he shared his insights into what’s behind this ‘massive amount of inventory’ on the market right now. I think we can all agree that sellers always list in the spring anyways but Ty lists a few new reasons as to why inventory has spiked.

The effect of government legislation.

The federal government released its housing strategy last month and we spoke about what that could mean for buyers and sellers in our article, Unpicking the Federal 2024 Budget. Sellers are trying to offload properties prior to the new capital gains taxation policy taking effect June 25th. While I don’t totally agree this will have the impact people think it will have on the sale of secondary residences, the move, compounded with the new BC short term legislation restrictions, makes for a compelling case to sell if you’re an investor in British Columbia.

Interest rates are still biting.

It’s pretty clear that buyers (and agents) anticipated at least one interest rate cut by June of this year. With less than a month until the next announcement on June 5th, I’m not so sure we still have that same optimism. Corsie predicts that even if there’s a reduction of 25 base points, there will be little effect on the market. Even if a rate decrease brings more consumer confidence, will enough buyers buy enough properties to balance out the market? I’m not so sure. With 12,000 listings on the market, it seems to be a buyer’s world out there.

Adding fuel to the fire, buyers who bought while interest rates were high, bought with the anticipation that rates will come down - we all thought this. That reality hasn’t quite come to fruition, so it also seems that homeowners simply can’t afford their mortgages any longer - there’s only so much stretch a budget can take before breaking.

Grass is always greener…

High costs of homeownership and high costs of living in general have people listing and relocating, often outside of BC.

Recent stats show nearly 70,000 people left BC last year - most of them to Alberta. This was the first time in more than a decade that more people left BC than moved here.

“It used to be a sell and a buy, staying in the same market,” says Corsie. “Now it’s a sell it and leave.”

Tips for buyers and sellers.

Key strategies for sellers right now? Set expectations and price accordingly. “Cheapest house on the nicest block mentality,” says Corsie.

Key strategies for buyers? They have a lot of choices right now, but it’s still super important to understand the nuances of specific neighborhoods and understand how absorption rate can still be different for specific types of properties depending on their needs and interests. Savvy agents know that when rates drop, competition gets fierce.

For me, stats in May are going to tell us a lot. Will buyers dive in and snatch up the properties available? Or will they keep waiting until mortgage rates start to dip?

📞 Your Next Step Starts Here—Contact Me Today!

Tara Kennedy
REALTOR® ABR, RENE, SRS
✨ Tara Kennedy Real Estate 🏘️
☎️ 236-992-8989
🌐 TaraKennedy.ca
📧 TaraKennedySells@gmail.com
🇨🇦 Royal LePage ELITE West

Always Putting Your Best Interest First! 🌟

Read
Reciprocity Logo The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.